What should a federal employee do with their Thrift Savings Plan (TSP) when the market is going down? Is it a good time to cut losses and move it all to the G fund? This was a major question in 2008 and 2009, and it makes a comeback every time stocks drop.
Before clicking that button to move everything to the G fund, I believe there are a couple of questions that you need to answer first.
- Why am I moving my money to the G fund?
- When will I move money back into the stock funds?
The most common answers I get to those questions are:
- I’m scared and I don’t want to lose anymore.
- I don’t know, but I want to wait for things to calm down.
Why are you moving your TSP to the G fund?
Let’s start with “I don’t want to lose anymore.” This isn’t a strategy but more of an emotional reaction, and emotional reactions have no place in an investment plan. Before anyone invests in stocks, they need to understand that there is volatility involved. It’s par for the course. Stocks (or funds made up of stocks, like the C, S and I funds) don’t go up in a straight line unless there is a guy named Bernie (Madoff) behind them!
In reality, your account value will fluctuate over time. Most long-term investors will experience at least a handful of down markets over the course of their lifetime. If you are working with an advisor, they should be able to show you what this looks like. If you are doing it on your own, I encourage you to do some research on market drawdowns and take note of the dollar impact they would have on your investments.
If you can’t handle seeing your account fluctuate, then you probably shouldn’t be invested heavily in stocks at all. Here is some information on market downturns and how often they happen.
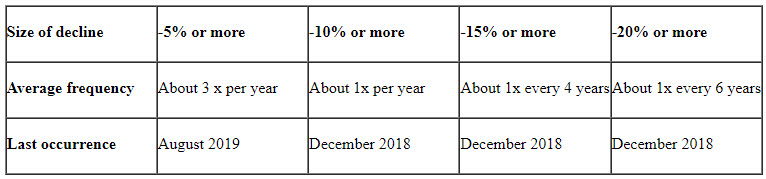
Sources: Capital Group, Standard and Poor’s
You can see from the chart above that most decades have at least one stock decline of 20% or more. A few recent examples: the S&P 500 fell about 34% in roughly five weeks in early 2020, about 25% during 2022, and nearly 19% in the spring of 2025. Each one felt like the bottom was nowhere in sight while it was happening.
If moving your money in and out of the G fund is part of your strategy, then you should have a good answer to the next question.
When do you get back in?
Getting back into the market is the toughest part of getting out. Once you get out, you really need to know where the bottom is going to be in order to get back in. If you think the market is going down 20% and it only goes down 15% and goes back up from there, you have just missed out and negated the move out of the market.
There is a TSP-specific wrinkle too. The TSP allows two interfund transfers per month. After those two, any additional transfers that month can only move money into the G fund. So if you bail out late in a month and the market turns, you may not be able to get back into the stock funds until the next month.
To help prove my point, I’d like to share a story about a famous investor and my own experience.
The Buffett bet
Many of you may recall that Warren Buffett made a million-dollar bet in 2007 with a hedge fund manager. The bet was that an S&P 500 index fund would outperform a basket of five funds of hedge funds over the next decade. The decade started in 2008 and ended in 2017.
Hedge funds typically try to make money in any kind of market environment, or at the very least they attempt to protect money when the market is going down and make money while it’s going up. Knowing that, you would think the time frame, which started with the 2008 crash, would be perfect for a hedge fund to beat an index. Also note that most hedge fund managers are very bright individuals, many of whom have earned a PhD, have advanced mathematics degrees, etc.
Despite a drawdown of over 50% along the way, the S&P 500 index fund gained 125.8% over the ten years. The five funds of funds gained between 2.4% and 87.7%.
Keep in mind that we are comparing investing, and staying invested, in a stock index to some of the more sophisticated investments that you can find, managed by some of the brightest minds in the investment world, and the boring index won by a ton! Not even the best of the five beat the index.
What I saw during the 2008 drawdown
From 2008 to 2012, I probably did around 80 seminars for federal employees throughout the Midwest. The question I was asked everywhere I went was, “What do I do with my TSP?” And the most common thing I was told in 2008 and, yes, the first half of 2009 was, “I couldn’t handle it anymore, I moved everything to the G fund.” As it turned out, early 2009 was the absolute worst time to do that. I don’t recall one person telling me that they were moving all of their money to the stock funds in that time period.
Fast forward to 2011 and 2012 and it was still common for someone to approach me and say that they moved everything to the G fund in 2009 and had been sitting on the sidelines waiting for the right time to get back in.
It still happens. Every time the stock market goes down, a lot of TSP participants choose the wrong action. Transfers into the G fund tend to spike when stocks are falling because way too many investors let their emotions drive their investment decisions.
After reading my experience and Buffett’s bet, my questions are:
- Are you smarter than hedge fund managers?
- How did you react to the last big market drop?
The first question isn’t meant to be funny, but a serious question. If hedge fund managers with advanced degrees on the subject can’t beat a simple index, then why would the average federal employee expect to?
Your reaction to the last market downturn will tell you a lot about your risk tolerance. However, people’s risk tolerance can change as they get older and experience different life events.
What happens to the market after a 25% drop?
No, there is never a guarantee when you are investing in stocks. But if you look at the history of the stock market, future returns have looked a lot better after a 25% drawdown than at other times. This video on TSP declines in context shows what the stock market has done in the past after dropping 25% or more.
The recent examples above fit that pattern. The S&P 500 was back to a new high by August 2020 after the early 2020 drop, by January 2024 after the 2022 decline, and by the end of June 2025 after the spring 2025 drop. Someone who moved to the G fund near any of those lows and waited for things to calm down likely missed a big part of the recovery.
Is the G fund a safe place to wait?
The G fund doesn’t lose value, and that is exactly why it feels good in a down market. But it has its own risk. As of June 30, 2026, the G fund averaged 2.89% a year over the past ten years, which may barely keep up with inflation and taxes over a long retirement. Every TSP fund has a risk, and I go through each one in all TSP funds can be bad.
I’m not saying you should never use the G fund. It can be a sensible place for money you will need in the next few years. I’m saying that moving everything there because the market dropped is a decision driven by fear, not a plan.
What should you do with your TSP when the market drops?
If you work with an advisor, this is the time when they prove their worth. Call and talk about your concerns and get some feedback. Sometimes people enter a different stage of life or have had lifestyle changes that warrant an allocation change. The time for that change may not be after a 25% market drop, though. Any change to your allocation should be well thought out before you make it.
A few things to consider instead:
- Rebalance. If stocks have fallen below your target, rebalancing means selling some G or F fund and buying stocks at lower prices. If you are in an L fund, it rebalances for you; I cover the pros and cons in the good and bad of lifecycle funds.
- Keep contributing. If you are still working, every paycheck buys shares at lower prices. If you have cash, maybe you want to invest some of it now.
- Look at tax moves. A down market can be a good time for a Roth conversion, since the same number of shares converts at a lower value. Since January 28, 2026, you can do in-plan Roth conversions inside the TSP, paying the tax from outside money; see Roth TSP conversions. Tax-loss harvesting is another option, but only in a taxable account, not in the TSP.
I go through more of these in smart actions in a market downturn, and this video on TSP and other actions in a down market covers them as well.
There are a number of actions you could take, but the most prudent action may be to do nothing. Stay put.
Market drawdowns can be very nerve-wracking, but they don’t have to be. Make sure you understand your long-term goals and invest accordingly. If you find times like these especially rough, it may be time to seek the help of a qualified advisor. You can see how we work with federal employees, and if you would like to have a conversation and see if we are a good fit, schedule an introductory call. I’d be happy to talk with you and discuss your options.
Brad Bobb, CFP®, Bobb Financial, is an expert in federal benefits and retirement planning for federal employees.
This article is for educational purposes only and is not individualized financial advice. Figures are illustrative.